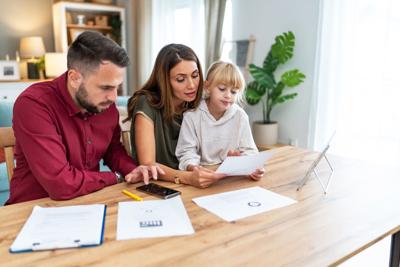

Young family with a daughter feeling stressed managing budget and paying bills and taxes
The financial demands of raising children rarely stay confined to diapers and daycare. They stretch across years, reshaping budgets, housing decisions, and long-term savings goals in ways that catch many families off guard. Rocket Mortgage's survey on financial planning for parents — drawing on responses from 1,007 U.S. parents and caregivers in December 2025 about the actual cost of raising children — reveals a striking gap between how prepared families feel and how their finances are actually holding up. While some parents are actively saving for the future, others are working through daily costs that came in higher than they initially expected. The data paints a complex picture of a generation of parents trying to balance immediate financial pressure with longer-term goals — and not always succeeding at both simultaneously.
People are also reading…
Planning Ahead Is Happening — But Not Always Keeping Pace
One of the more encouraging findings in Rocket Mortgage's survey is that 61% of parents are actively saving for future education costs. That means a meaningful majority of families are thinking beyond the present moment and trying to set aside resources for their children's academic futures — no small feat given how stretched many household budgets already are. But that forward-looking behavior exists alongside some challenging financial realities. Two-thirds of parents in the survey say raising children has cost more than they expected — a gap that makes long-term financial planning significantly harder to execute consistently. Planning for education when day-to-day expenses are already higher than projected is a genuine tension. For many parents, the question isn't whether they want to save — it's whether there's room in the budget to do it.
The Housing Decision as a Financial Planning Move
Long-term financial planning for parents doesn't happen in a vacuum — it unfolds alongside major life decisions, and few are larger than where and how a family chooses to live. Rocket Mortgage's research found that 43% of parents say having kids created a need for more physical space, while 41% say parenthood generated a stronger desire for stability, specifically in the form of owning rather than renting. These two findings together suggest that housing is itself a financial planning decision for many families — not just a lifestyle preference. Choosing to purchase a home rather than continue renting may reflect a desire to lock in a stable cost structure, build equity over time, and create a foundation that supports the family's broader financial goals. For parents already managing higher-than-expected child-related expenses, homeownership may function as a potential hedge against rising rents and an asset that may contribute to long-term wealth. That said, transitioning from renting to owning comes with its own upfront costs, and finding the right timing takes planning — especially for families already managing higher child-related expenses.
When Current Costs Crowd Out Future Goals
Understanding why some families struggle to stay on track with long-term planning requires looking at what's happening to their budgets right now. Rocket Mortgage's survey found that 24% of parents saw their monthly spending increase by $1,000 or more after having children. Among the biggest drivers of that increase: food and household goods, cited by 38% of respondents as a top cost category, and child care, named by 29%. Child care costs, specifically, carry particular weight. Among the 54% of survey respondents who pay for child care, nearly a third — 32% — report spending between 20% and 29% of their total household income on it. That's a substantial slice of a family's resources going to a single expense, leaving less available for debt repayment, emergency savings, or longer-term goals like education funds or retirement contributions. It's perhaps unsurprising, then, that 58% of parents have gone into debt — through credit cards or loans — as a result of child-related expenses. Debt accumulated in the early years of parenthood can have compounding effects on a family's financial trajectory, making it harder to build savings momentum even when income grows over time.
The Emotional Cost of Financial Uncertainty
Financial planning is often discussed in purely numerical terms — savings rates, debt-to-income ratios, emergency fund targets. But Rocket Mortgage's survey data makes clear that for parents, money stress isn't just a spreadsheet problem. It's an ongoing emotional experience. Forty-six percent of respondents say child-related finances cause them stress always or usually. That's nearly half of all parents living with persistent financial anxiety. The survey also found that 50% of parents have delayed or avoided having additional children due to financial concerns. When money pressure is significant enough to influence family-building decisions, it signals that financial planning isn't just an abstract goal — it's a genuine need that many families are actively struggling to meet.
The Desire Is There, The Tools Aren't
Rocket Mortgage's survey of 1,007 U.S. parents makes one thing clear: The desire to plan ahead financially is present, but the conditions that make planning easy often aren't. The majority of parents are saving for education, and many are making housing decisions with long-term stability in mind — yet those same families are managing unexpected monthly costs, significant child care expenses, and debt accumulated along the way. Acknowledging this tension is a useful starting point. Parents who understand where their money is actually going — and where the gaps between intention and execution exist — may be better positioned to close them, even gradually, over time.